
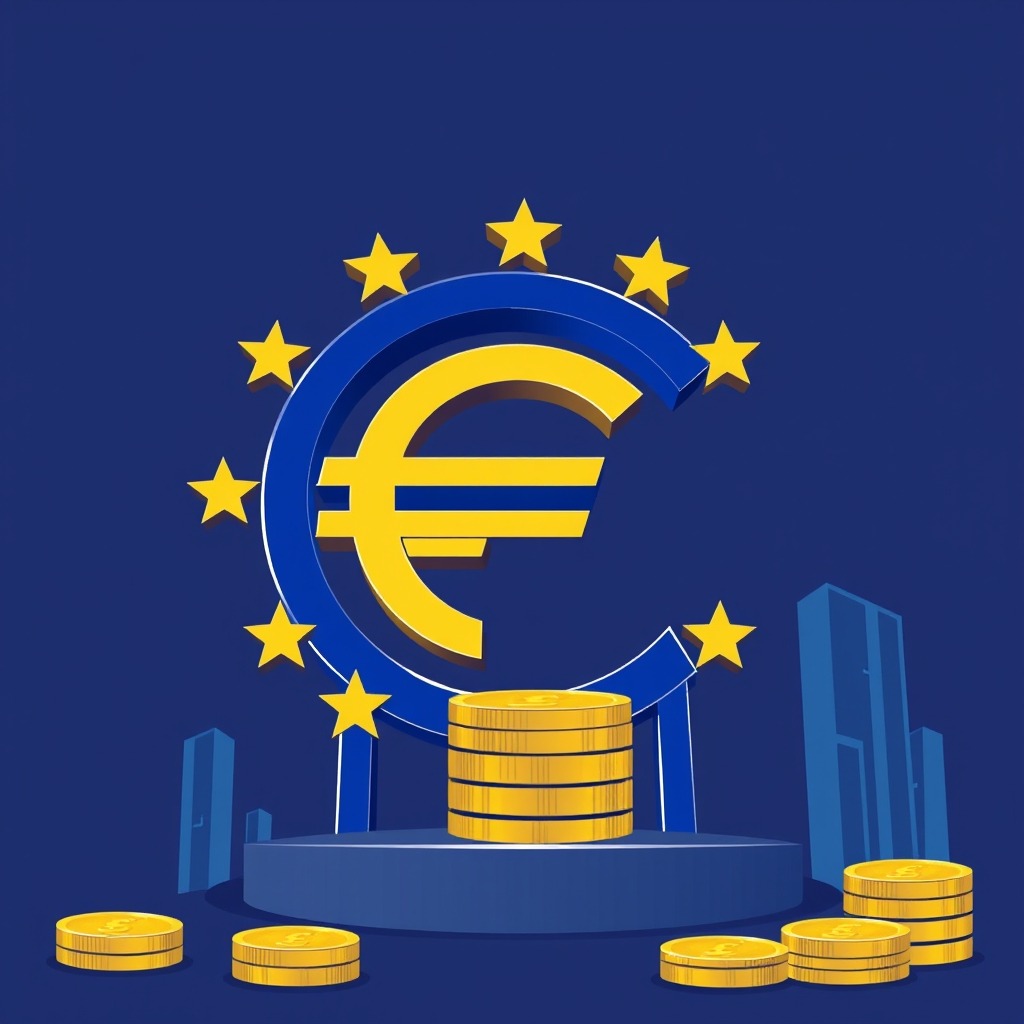
The digital euro debate just got a sharper edge, with a European Central Bank board member warning that Europe risks financial fragmentation if it does not launch its own central bank digital currency. The pitch is notable for what it is not: the official stressed that a digital euro would not take over the role of banks, but rather keep them embedded in the region’s monetary system. For crypto traders, this is a window into how a major economic bloc plans to answer stablecoins and private digital money.
What Happened
An ECB executive board member argued that the absence of a digital euro could leave Europe’s payments landscape fragmented and overly dependent on external providers. The framing was defensive and strategic at once: a CBDC as a way to preserve monetary sovereignty and a unified payments rail, not as a tool to disintermediate commercial banks.
That reassurance to banks is deliberate. One of the loudest objections to retail CBDCs is that citizens might move deposits out of commercial banks and into central bank money, draining the funding banks rely on to lend. By insisting the digital euro would keep banks in the loop, the ECB is trying to defuse that fear before it stalls the project.
What It Means for Traders
A digital euro would compete most directly with euro-denominated stablecoins. If the ECB builds a credible public alternative, it could cap how far private stablecoins penetrate European payments, which matters for anyone trading or holding those instruments. The competitive line between public and private digital money is being drawn now.
There is also a liquidity angle. Central bank concerns about deposits leaving the banking system are really concerns about funding and credit conditions, and tighter credit conditions tend to drain liquidity from risk assets, crypto included. How the digital euro is designed, including any holding limits, will shape whether it is a mild payments upgrade or a deeper change to how money moves.
For now, the signal is directional rather than immediate: Europe is moving toward public digital money, and traders should track the design choices that determine its competitive reach.
The Bigger Picture
The deposit-flight worry is a recurring theme in European policy. The same institution has previously warned that stablecoins could erode bank deposits, and a digital euro is partly a response to that exact pressure. The CBDC and the stablecoin question are two sides of one debate about who issues the digital money Europeans use.
Macro context sharpens the stakes. The ECB is already managing liquidity through its balance sheet, a dynamic explored in how Bitcoin competes with the ECB’s bond runoff for a shrinking liquidity pool. Public appetite is not the obstacle it once seemed either, given earlier findings that a large share of some European citizens would hold a digital euro.
Globally, CBDC momentum pressures the entire stablecoin and crypto-payments sector to prove it offers something public money cannot, whether that is openness, programmability, or cross-border reach.
The Bottom Line
The ECB’s fragmentation warning signals that a digital euro is being framed as a strategic necessity, not an experiment. For traders, the key is design: holding limits, bank integration, and timeline will decide how hard a digital euro competes with stablecoins and how it shapes euro-area liquidity in the years ahead.
This article is informational only and does not constitute financial advice.